Case #014 • Year-End Tax Planning | Taxes
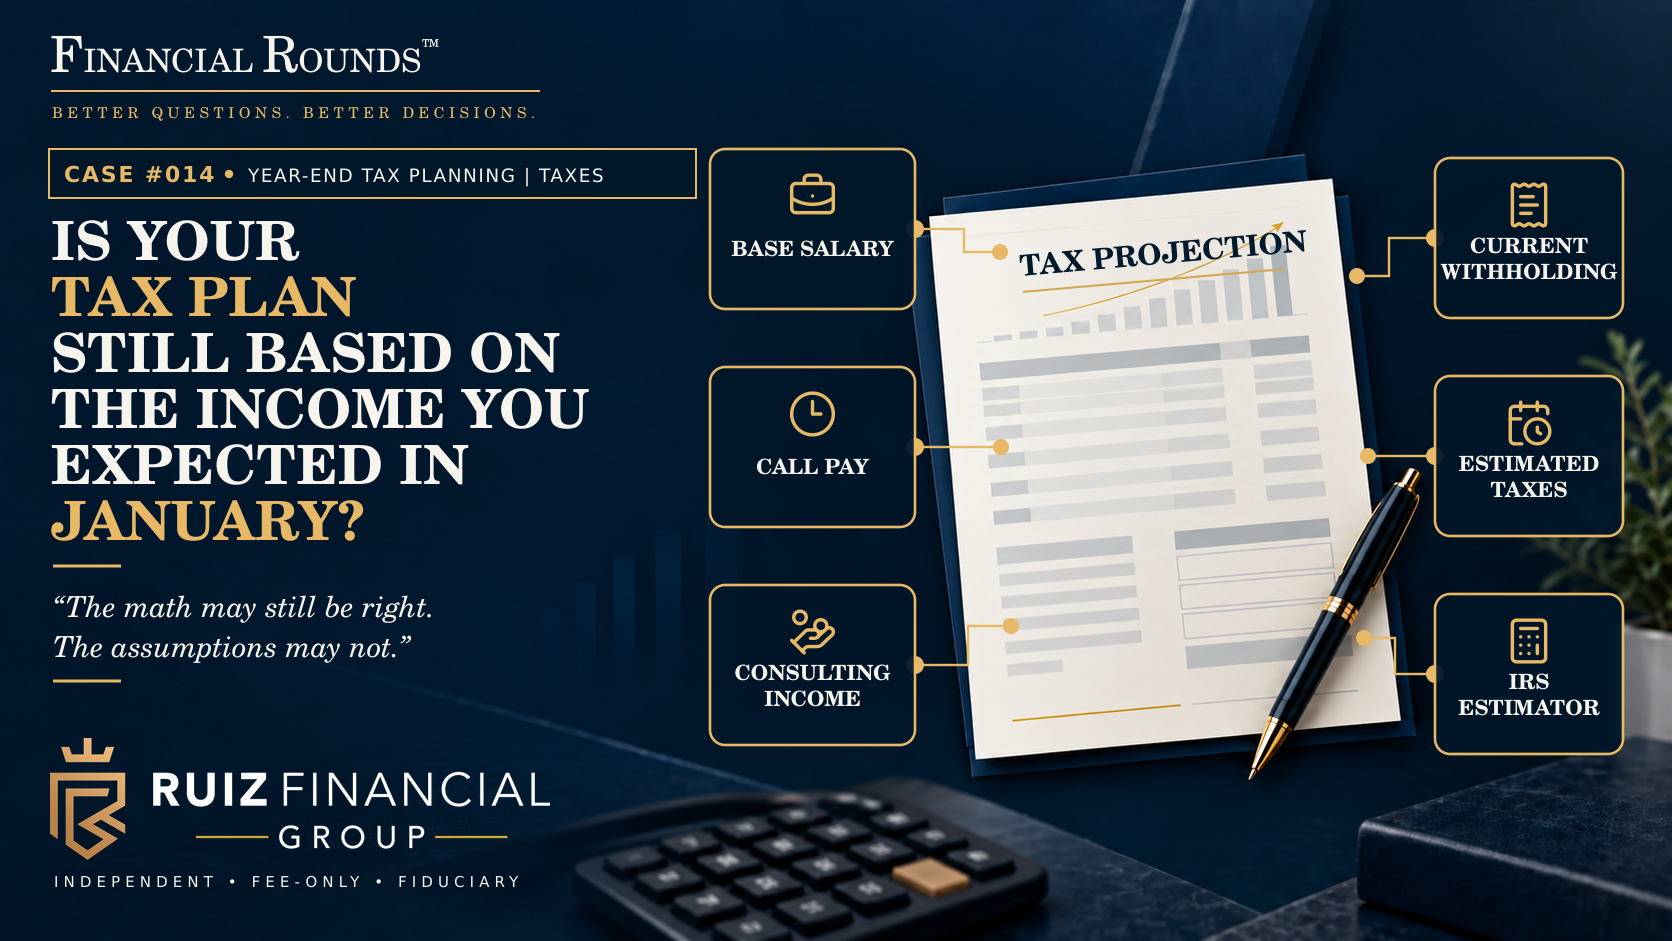
In January, a physician reviews what the coming year is expected to look like. Her base salary should be approximately $325,000, call pay may add another $15,000, and a small consulting arrangement is expected to generate about $20,000.
Using those figures, she prepares a tax projection, reviews her payroll withholding, and schedules estimated tax payments for the consulting income. The numbers appear reasonable, the payments are arranged, and taxes feel handled for the year.
Then the year changes.
Staffing shortages lead to more call shifts than expected. The consulting work expands gradually as one project leads to another. Neither development feels dramatic enough on its own to trigger a new tax review, but by November, her income no longer resembles the year she projected in January.
Her paychecks still show federal taxes being withheld, and every scheduled estimated payment has been made. She has not ignored her taxes or missed a payment. She has followed the plan exactly as it was created.
The reasonable first question is:
Am I on track with my taxes for this year?
The better question is:
Does my tax projection reflect what actually happened—or what I expected to happen in January?
Why This Matters
A tax projection is a picture of the year built from the information available at a particular moment. In January, that picture may be entirely reasonable. The difficulty is that the projection does not update itself when the year unfolds differently.
An additional call shift rarely feels like a reason to revisit a tax plan. Neither does a single consulting payment. When those changes accumulate over several months, however, the difference between expected income and actual income can become meaningful without producing an obvious warning along the way.
That is what makes stale assumptions easy to miss. Withholding continues to appear on each paycheck, and estimated payments leave the bank account on schedule. Everything looks organized because the payment process is working—even though the amounts being paid may still be connected to an earlier version of the year.
The IRS Tax Withholding Estimator can be a useful reference when reviewing federal income tax withholding from paychecks. Like any projection tool, however, its result depends on the income and payment information entered into it.
The objective is not to predict the final tax return perfectly. It is to recognize when the facts have changed enough that the original projection deserves another look while there may still be time to respond.
The Diagnosis
Return to the physician’s January projection. It assumed $325,000 of base salary, $15,000 of call pay, and $20,000 of consulting income—a projected total of $360,000.
By November, her base salary remains on track, but call pay is expected to reach approximately $45,000 and consulting income is approaching $40,000. The year is now tracking toward $410,000, or about $50,000 more income than the original projection anticipated.
Nothing about the January calculation was necessarily wrong. It used the information available at the time, and the physician followed the resulting plan. Payroll withholding continued, and the estimated payments were made as scheduled.
The problem is that the projection is still answering the question it was given in January. It does not know that call pay tripled or that consulting income doubled unless someone gives it the new information.
The physician did not fail to follow the plan. The plan simply did not follow the year.
The diagnosis: The math may still be right. The assumptions may not.
The Treatment
A useful year-end tax review begins by replacing the expected year with the year that is actually taking shape. That means gathering available year-to-date figures for base salary, call pay, consulting income, and any other material compensation, then developing a reasonable estimate for what remains.
Separating those sources can matter because they may arrive through different payment arrangements. Base salary and call pay may flow through payroll, while consulting income may arrive without the same withholding. Looking only at total income—or only at what has already been withheld—can obscure how the pieces fit together.
Taxes already paid should then be viewed alongside the updated income projection. Withholding on the physician’s paychecks did not disappear, and her estimated payments were not wasted simply because the original assumptions changed. The question is whether those payments still make sense in relation to the year now expected.
For someone whose income is primarily reported through payroll, the IRS Tax Withholding Estimator may help evaluate current federal withholding. A situation involving several income sources or more complicated tax considerations may require a broader projection and coordination with a qualified tax professional.
Once the assumptions have been updated, the appropriate response may be adjusting payroll withholding, revisiting an estimated tax payment, reserving additional cash, or determining that no change is necessary. The purpose of the review is not to assume that higher income automatically creates a problem. It is to make the next decision using current information rather than January’s expectations.
A tax projection is not a document to complete once and file away. It is a working estimate, and its usefulness changes when the financial life underneath it changes.
Practical Takeaways
- Compare the actual year with the year originally projected. Review base salary, call pay, consulting income, and other material compensation changes instead of relying on what was expected in January.
- Evaluate taxes paid against the updated income picture. Withholding and estimated payments may both be occurring as planned while still reflecting assumptions that are no longer current.
- Revisit the projection after a meaningful change. Additional work, a compensation adjustment, or a new income source can make an earlier projection less relevant even when its original calculations were correct.
Bottom Line
A tax projection does not become outdated because the mathematics stopped working. It becomes outdated when the assumptions no longer describe the year that actually occurred.
For healthcare professionals with call pay, consulting income, bonuses, or other variable compensation, those differences can accumulate quietly. The payments may be occurring exactly as scheduled while the schedule itself is still based on an earlier version of the year.
Before relying on an existing projection, ask whether the income, withholding, and estimated tax payments underneath it are still current. The better year-end question is not simply whether the original projection was correct. It is whether that projection is still answering the right question.
What else does it touch?
Continue Learning
• Explore which changing financial information actually deserves your attention →
Case #007: What Belongs on Your Financial Dashboard?
• Explore why a one-year tax calculation may not capture the full decision →
Case #008: When Does a Roth Conversion Actually Make Sense?