

Case #004 • Earning Power and Financial Independence
Why This Matters
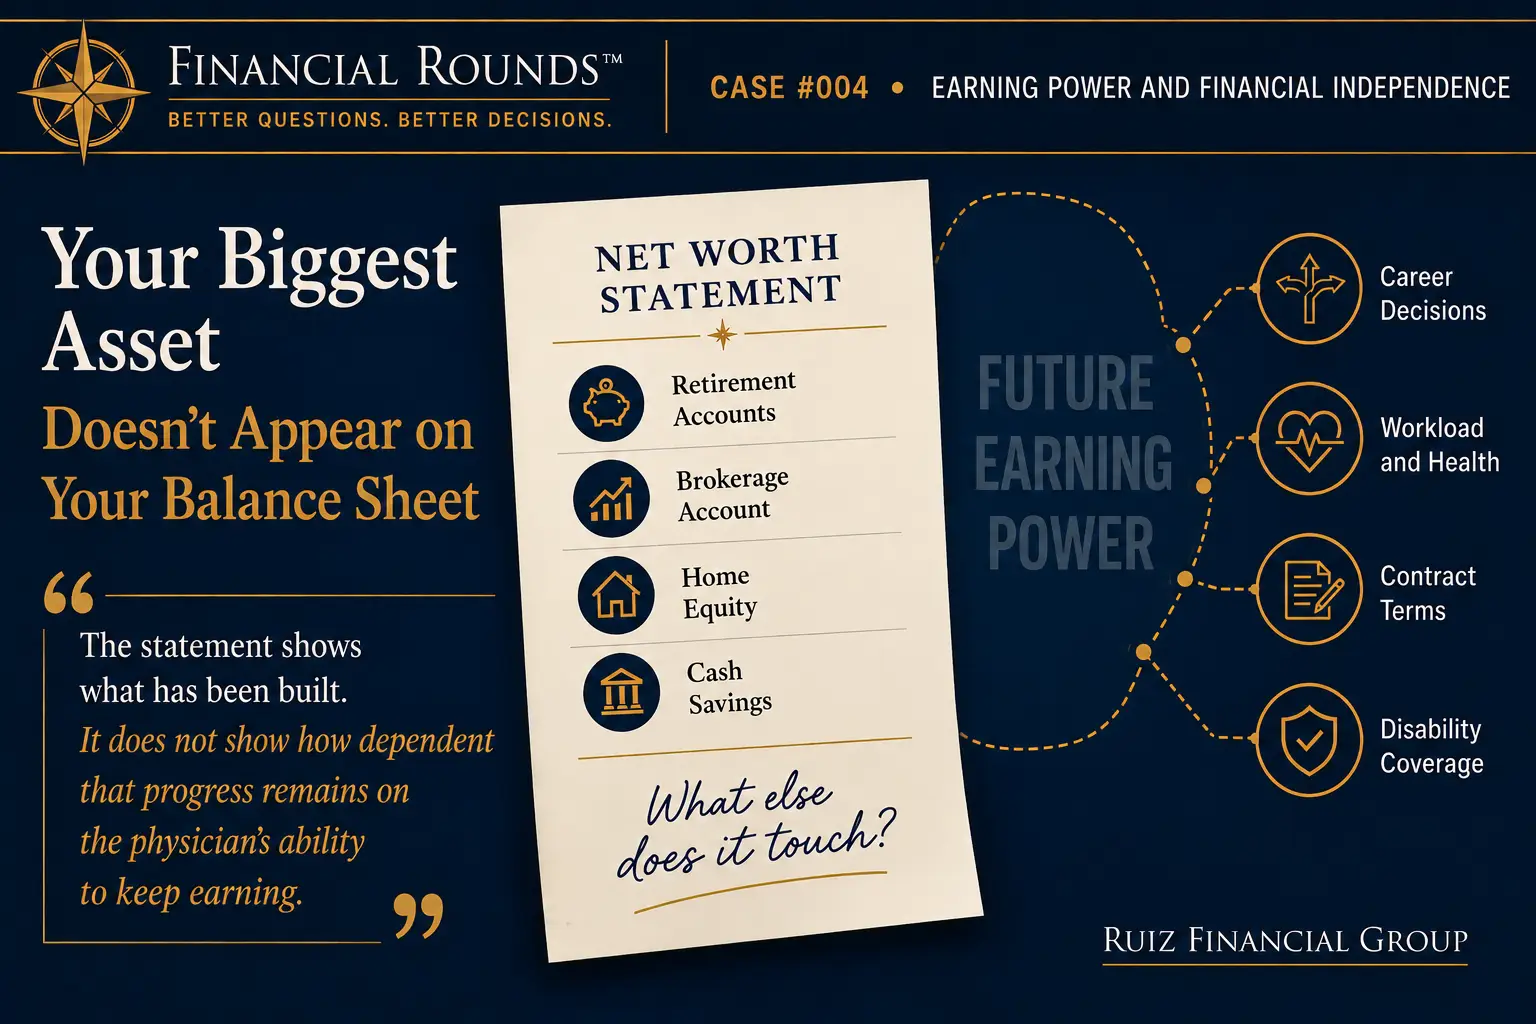
Imagine reviewing your net worth statement. Retirement accounts, a brokerage account, some home equity, maybe a savings buffer. Everything looks accounted for.
But for many physicians, especially earlier in a career, one of the largest drivers of future financial independence isn’t listed anywhere on that page. Physician earning power may be one of the most valuable financial assets a physician has.
That’s easy to overlook because it never appears as a line item on the statement itself. It’s worth understanding before making decisions that quietly affect it.
The Diagnosis
The reasonable first question is:
How much have I accumulated?
That’s a fair thing to track. It’s also incomplete because accumulation is a lagging indicator. It shows what past earning power has already produced, not what may produce the next twenty years of progress.
Consider a physician a few years into practice who feels genuinely on track. Retirement contributions are automated, a home has real equity, and savings look healthy.
When an extra weekend shift comes up, it is an easy yes: more income and more progress toward numbers already moving in the right direction.
When an opportunity to review disability coverage comes up, it is easy to postpone. The premium feels like another fixed cost competing with a monthly budget that is otherwise working.
Neither decision looks like a mistake from the net worth statement. The statement shows what has been built. It does not show how dependent that progress remains on the physician’s ability to keep earning.
The better question is:
What’s actually producing my future wealth, and what could interrupt it?
The Treatment
Several ordinary decisions connect to physician earning power more directly than they first appear.
Career and specialization choices shape both current income and its trajectory over time.
Health and workload affect how sustainable that income is.
Disability coverage helps address what happens if illness or injury interrupts it.
Contract terms influence how much flexibility and control remain available as circumstances change.
These are not separate line items competing for attention. They are different angles on the same underlying asset.
The point isn’t to optimize every one of them. It’s to recognize that a statement showing healthy accumulation can still depend heavily on an asset that has gone largely unexamined.
Practical Takeaways
- Ask what’s currently producing your future wealth, not just what’s already accumulated.
- Treat decisions about workload, specialization, contracts, and coverage as connected to the same underlying asset.
- Evaluate the risks to future earning power with the same seriousness given to the assets that earning power is building.
Bottom Line
Every financial statement accurately tells you what you own. It does not show the physician earning power that made owning it possible.
Before making a decision that touches your income, workload, career, or coverage, ask:
What else does it touch?
Continue Learning
• Read another Financial Rounds™ case → Case #003: Before You Say Yes
• Explore a physician guide covering related financial decisions → 9 Money Mistakes Doctors Make