Case #015 • Changing Employers | Transition
A physician giving notice at a hospital system usually has one number on her mind: the balance in her 403(b).
It has been building for nearly five years and is, by a wide margin, the largest account shown on her statement. So when she starts planning the move to a new employer, that account gets her attention first. Depending on the plans involved, she may be able to leave the money where it is, move it to the new employer’s plan, roll it to an IRA, or take a distribution. The IRS outlines these possible paths, but she wants to understand the differences and get the decision right.
What she is not expecting to learn is that $6,400 of the employer contributions shown on her statement has not vested—and will not go with her when she leaves.
The reasonable first question is:
What should I do with my old retirement plan?
The better question is:
What else changes financially when I leave this employer?
Why This Matters
The retirement account is the easiest thing to see during a job change. It has a balance, paperwork, and a decision attached to it. It feels like the financial event.
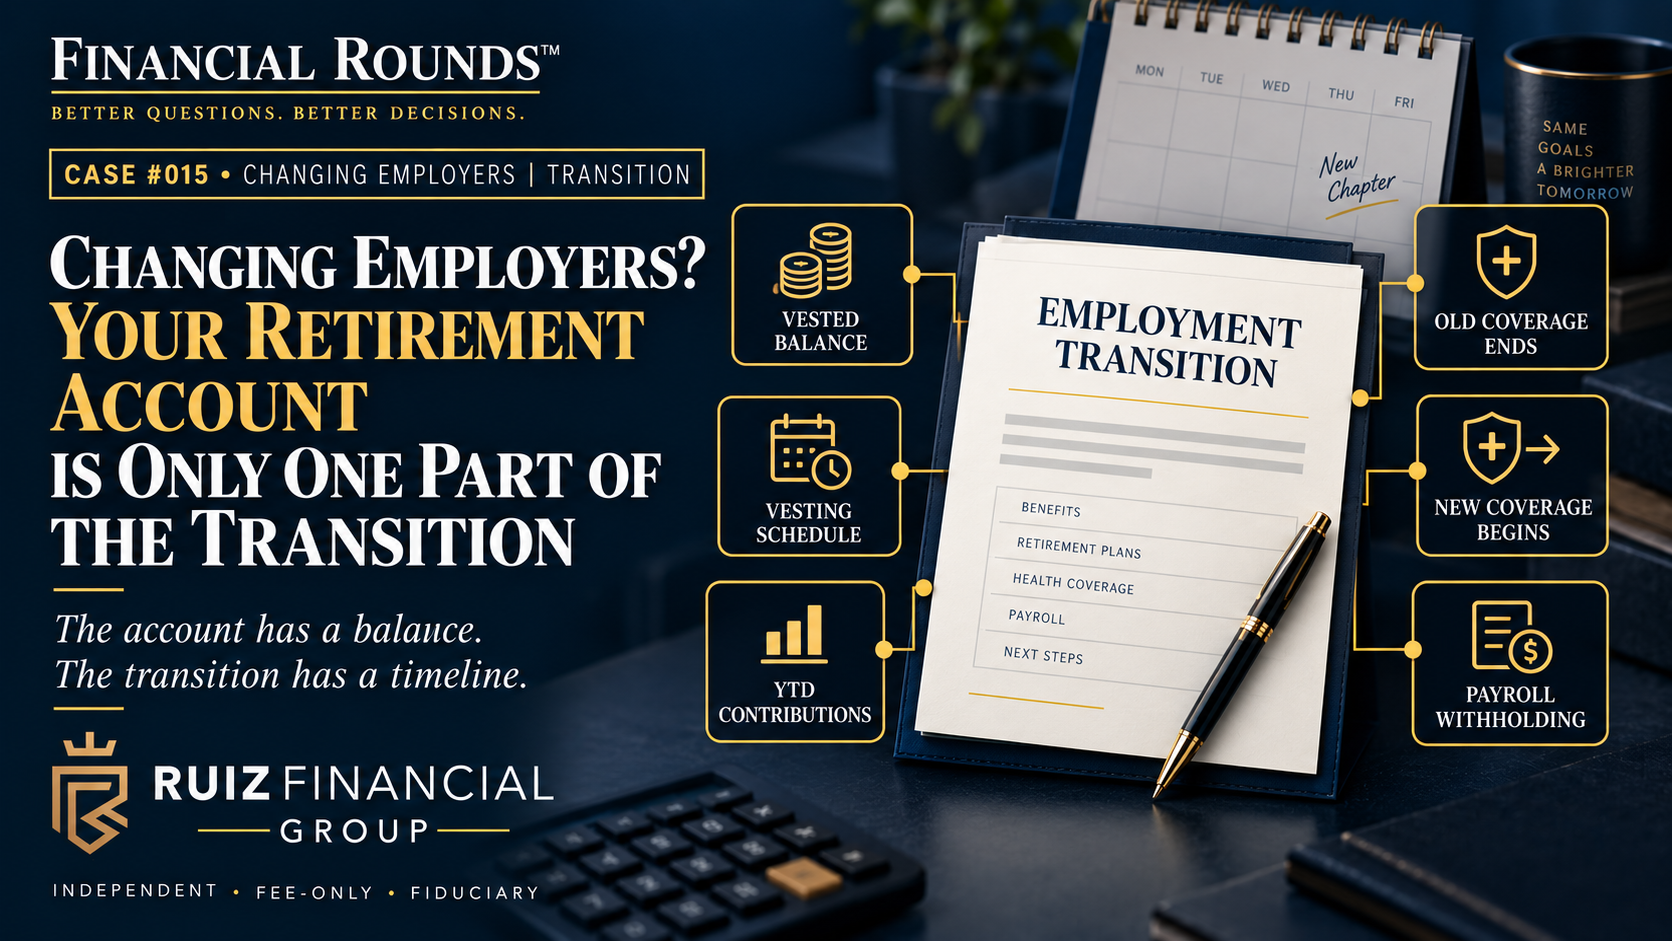
Everything else about the transition is quieter. A vesting schedule that never came up in casual conversation. A health plan that ends on a specific date, followed by a new plan that does not begin on that same date. Two employers issuing paychecks during the same year, each operating with its own payroll information and withholding elections.
None of these issues announces itself the way a six-figure account balance does. That is exactly why they can be easy to miss.
The Diagnosis
Go back to the physician and her 403(b).
Her plan uses a graded vesting schedule for employer contributions. Under this particular plan, she earns another 20% of ownership after each completed year of service and becomes fully vested after five years. The plan measures those completed years using her employment anniversary date.
She has worked there for four years and ten months. Her own contributions are entirely hers, but she is only 80% vested in the $32,000 contributed by her employer. Because her final day falls two months before her fifth anniversary, the remaining 20%—$6,400—is unvested and, under the terms of this plan, is forfeited after her departure.
She had assumed that everything shown on the account statement belonged to her. Most of it does, but not all of it.
Nothing about her analysis of the retirement account was careless. She correctly identified the balance, compared the available options, and considered the fees and investment choices under the old and new plans. The calculation involving the account itself held up.
The problem was the assumption underneath it: that the total balance shown on the statement was the same as the amount she owned.
Meanwhile, a second issue was unfolding on a different timeline. Her health coverage under the old employer ended on her last day, while the new employer’s plan did not begin until the first of the following month. That created seventeen days without active employer coverage—a gap she did not notice until she tried to schedule a routine appointment and was told that her insurance was inactive.
The diagnosis: A retirement account can be evaluated correctly and still leave the biggest surprises of the transition unexamined. The account has a balance. The transition has a timeline—and vesting, coverage, and compensation can each run on timelines of their own.
The Treatment
The fix is not a longer checklist. It is a different starting question.
Instead of beginning with the account and working outward, begin with the calendar. What is the final day of employment, and what changes immediately before or after it?
For the retirement plan, that means reviewing the Summary Plan Description and determining how the plan calculates vesting service. Vesting schedules and methods for counting service vary by plan, so the timing that matters for one employee may not apply to another. The important figures are not merely the total balance and years worked, but the vested balance, the plan’s service-counting method, and whether the anticipated departure date falls before or after the next vesting milestone.
For health coverage, the same calendar should show the exact date the old plan ends and the exact date the new plan begins. If those dates do not meet, the gap can be addressed deliberately rather than discovered when someone attempts to use the coverage.
Retirement contributions deserve a separate review from the decision about where the old account should be held. When the old and new plans share the same employee elective-deferral limit, contributions already made during the year generally continue to count toward that limit. The new employer’s paperwork may look like a fresh start, but the calendar-year contribution calculation may not begin again at zero.
The first new paycheck also deserves attention. A different salary, signing bonus, productivity formula, or source of outside income can make the withholding elections that seemed reasonable in January less accurate by the time the new compensation begins.
None of this replaces the retirement-account decision. It sits alongside it. The account has a balance that is easy to evaluate; the rest of the transition has a shape that is easier to miss.
Practical Takeaways
- Confirm the vested balance and read the actual vesting provisions. Do not estimate ownership from years of employment or assume that the total account balance is fully vested. Determine how the plan counts vesting service and compare the next vesting milestone with the anticipated departure date.
- Map the health-coverage dates before the transition. Line up the exact end date of the former employer’s coverage with the exact start date of the new plan, then address anything that falls between them.
- Coordinate the new job with the year already in progress. Employee retirement contributions already made and taxes already withheld do not disappear when employment changes. Review the new elections in the context of the entire year.
Bottom Line
The retirement account gets most of the attention during a job change because it is the easiest thing to see.
But a vesting schedule, a coverage gap, and a withholding assumption do not wait for someone to notice them. They continue running on their own timelines, whether or not the account decision is receiving careful attention.
Before finalizing what happens to the old account, find out what else is quietly happening on the way out the door.
What else does it touch?