Case #013 • Catch-Up Contributions
The rules for catch-up contributions in 2026 can create unexpected decisions for employees age 50 and older, particularly when higher contribution limits and Roth requirements intersect.
In January, a physician who will turn 60 in October reviews her retirement-plan election for the coming year. She has maximized her 403(b) for several years, so the process feels familiar: determine the regular contribution limit, add the age-50 catch-up amount, and adjust payroll accordingly.
She expects to contribute $32,500 during 2026—the regular $24,500 employee-deferral limit plus an $8,000 catch-up contribution. She also assumes those dollars can receive the same pre-tax treatment she selected in prior years.
Later, her employer’s benefits department gives her two pieces of information she was not expecting. Because she will turn 60 during 2026, she may qualify for a higher catch-up contribution. Because her 2025 FICA wages from that employer exceeded $150,000, the catch-up portion may also need to be contributed on a Roth basis.
She may be able to contribute more than she anticipated, but the additional dollars may not affect her current taxable income the way she expected.
The reasonable first question is:
How much catch-up contribution am I allowed to make?
The better question is:
Which catch-up rules actually apply to me this year?
Why Catch-Up Contributions in 2026 Matters
For 2026, participants age 50 or older may be permitted to make an additional $8,000 catch-up contribution to most 401(k), 403(b), and governmental 457(b) plans. Combined with the regular $24,500 employee-deferral limit, that can bring the potential employee contribution to $32,500.
Employees who turn 60, 61, 62, or 63 during 2026 may instead qualify for a higher $11,250 catch-up contribution. For an eligible participant, that can increase the potential employee contribution to $35,750. The higher catch-up replaces the standard $8,000 catch-up for the year; the two amounts do not stack.
Beginning in 2026, another rule can affect how the catch-up contribution is treated. Participants whose prior-year wages from the employer sponsoring the plan exceeded $150,000 generally must make their catch-up contributions on a Roth basis when the applicable plan offers catch-up contributions through a Roth feature.
The wage test is tied to prior-year wages from the employer sponsoring the plan. It is not simply based on total household income or compensation from every source.
That means two physicians who are both over age 50—and who both intend to maximize their retirement plans—can face different contribution limits and different tax treatment. The IRS catch-up contribution guidance summarizes the applicable 2026 limits and Roth catch-up requirement.
The Diagnosis
Return to the physician who will turn 60 in October. Her original payroll election was designed to reach $32,500 because she assumed the standard age-50 catch-up applied.
Her age changes that calculation. Because she will turn 60 during the calendar year, her plan may permit an $11,250 catch-up instead of $8,000. That gives her an additional $3,250 of potential retirement-plan room and increases the possible employee contribution to $35,750.
Her prior-year wages create a second change. Suppose she received $184,000 of 2025 FICA wages from the employer sponsoring the plan. Because that amount exceeded the $150,000 threshold, her 2026 catch-up dollars generally must be designated as Roth if the applicable requirement applies under the plan.
Her regular employee deferrals may still follow the election available under the plan, but the catch-up portion can receive different tax treatment. Roth catch-up contributions do not reduce current federal taxable income in the same way as pre-tax salary deferrals, although qualified Roth distributions can be tax-free later.
The physician has not lost the ability to make a catch-up contribution. In fact, she may have more contribution room than she expected. What changed is the amount available and how the additional dollars may be taxed.
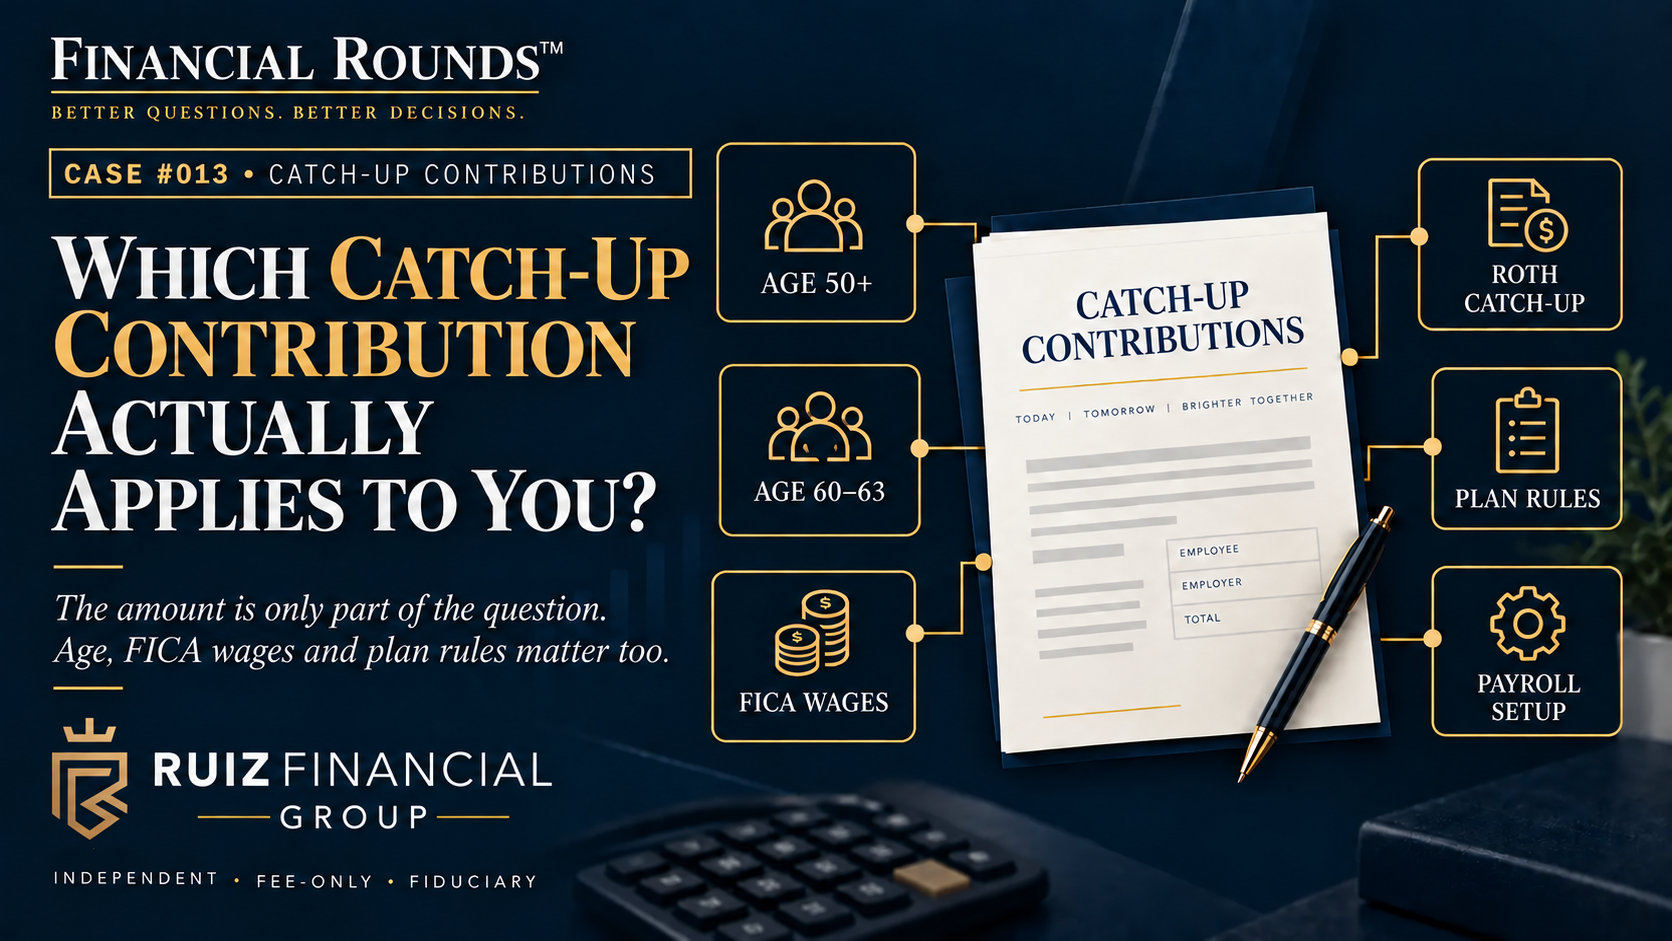
The diagnosis: The amount is only part of the question. Age, prior-year FICA wages, and plan rules can change both the contribution room available and the tax treatment of the dollars that fill it.
The Treatment
A better catch-up contribution decision begins with the participant’s age during the calendar year. Someone who is at least age 50 may qualify for the standard catch-up, while someone who turns 60, 61, 62, or 63 during the year may qualify for the higher amount instead.
The next part of the analysis connects the current contribution election to the prior year’s wages. For 2026, the relevant threshold is more than $150,000 of 2025 wages from the employer sponsoring the plan. That distinction matters because compensation from another employer, investment income, or a spouse’s earnings does not answer the same question.
The employer’s plan provisions and payroll system then determine how those rules are implemented. The plan must permit catch-up contributions, and payroll must distinguish between regular elective deferrals and contributions treated as catch-up dollars. An employee who simply repeats a prior-year payroll percentage may therefore contribute less than intended or encounter a different Roth treatment than expected.
The tax projection and cash-flow plan may need attention as well. If catch-up dollars that were expected to be pre-tax must instead be Roth, current federal taxable income may be higher than anticipated. That can affect withholding, take-home pay, and the assumptions used in a year-end tax projection.
None of this means that Roth treatment is inherently better or worse. It means the contribution election should reflect the actual limit, the plan’s provisions, and the tax treatment that applies to the participant.
The available contribution room matters. So does the tax treatment of the dollars that fill it.
Practical Takeaways
- Know which age range applies. The standard age-50 catch-up and the higher catch-up for participants turning 60 through 63 are different limits.
- Check prior-year wages from the plan sponsor. For some higher-paid participants, a 2026 catch-up contribution generally must be made on a Roth basis.
- Coordinate the limit with payroll and tax planning. The contribution amount, plan provisions, Roth treatment, withholding, and expected take-home pay may need to be reviewed together.
Bottom Line
A catch-up contribution used to be easy to think of as additional retirement-plan room after age 50. In 2026, the answer can depend on age, prior-year wages from the plan sponsor, and the provisions of the employer’s plan.
The physician in this case gained $3,250 of contribution room by turning 60, but the catch-up dollars also received different tax treatment than she initially expected. Neither fact could be identified simply by asking whether she was old enough to make a catch-up contribution.
The useful question is not merely how much more you can contribute. It is whether you understand which rule applies to those additional dollars and what else that rule changes.
What else does it touch?
Continue Learning
• Explore whether your current payroll elections are actually on pace to reach your intended contribution →
Case #012: Are You Actually on Track to Max Out Your Retirement Plans?
• Explore why a tax decision can involve more than the amount of tax due today →
Case #005: The Tax Bill Isn’t the Problem