

How Your Financial Advisor Gets Paid Matters More Than You Think
The title “financial advisor” gets used across some very different business models. Before you decide whose advice to trust, it’s worth understanding who’s actually paying the person giving it.
Walk into a bank, sit down with someone at a large brokerage firm, talk to an insurance professional, work with an advisor affiliated with both a brokerage and an investment advisory firm, or hire an independent registered investment adviser. All of them might introduce themselves as your “financial advisor.” All of them might discuss your investments, retirement, insurance, taxes, or estate planning. But they are not compensated the same way, and that difference matters more than most people realize.
One of the biggest misunderstandings I run into with prospective clients is the assumption that advisors basically all work under the same model. They don’t. Over 18 years in this business, across banking, lending, institutional advisory, and private banking, I’ve worked under a few different compensation structures myself, and I’ve seen firsthand how confusing the distinctions can be for consumers. The industry doesn’t make it easier. Some of the terms sound nearly identical even though they describe very different relationships.
You don’t need to become an expert in financial-industry compensation to pick a good advisor. But you should understand who’s paying the person across the table from you, and whether that pay changes depending on what you decide to do.
Start With a Simple Question: Who Pays Your Advisor?
Say you’re paying someone directly for comprehensive financial advice. That advisor might look at your retirement accounts, investments, taxes, cash flow, benefits, insurance, estate plan, and everything in between. A lot of that work involves recommendations where there’s nothing for the advisor to sell.
An advisor might flag that your umbrella liability coverage looks thin. That doesn’t mean the advisor has to sell you the policy. Your estate plan might need updating. Your advisor doesn’t have to be the attorney drafting the documents to notice the gap and tell you to call one. Your auto insurance limits might be too low, with zero financial upside for the advisor either way, and it’s still worth flagging as part of looking at your whole financial picture.
That’s what comprehensive planning is supposed to do: consider how the pieces of your financial life connect, including the areas where the advisor never gets paid a dime more for saying something.
Now flip it. Say an advisor concludes you need more life insurance, and that same advisor earns a commission on whatever policy you buy. That doesn’t automatically make the recommendation wrong. But it raises a fair question: would the advice be any different if the advisor got paid the same regardless of what you decided?
Compensation creates incentives, and pretending otherwise doesn’t do anyone any favors. Knowing the incentive exists puts you in a better position to weigh the advice on its merits.
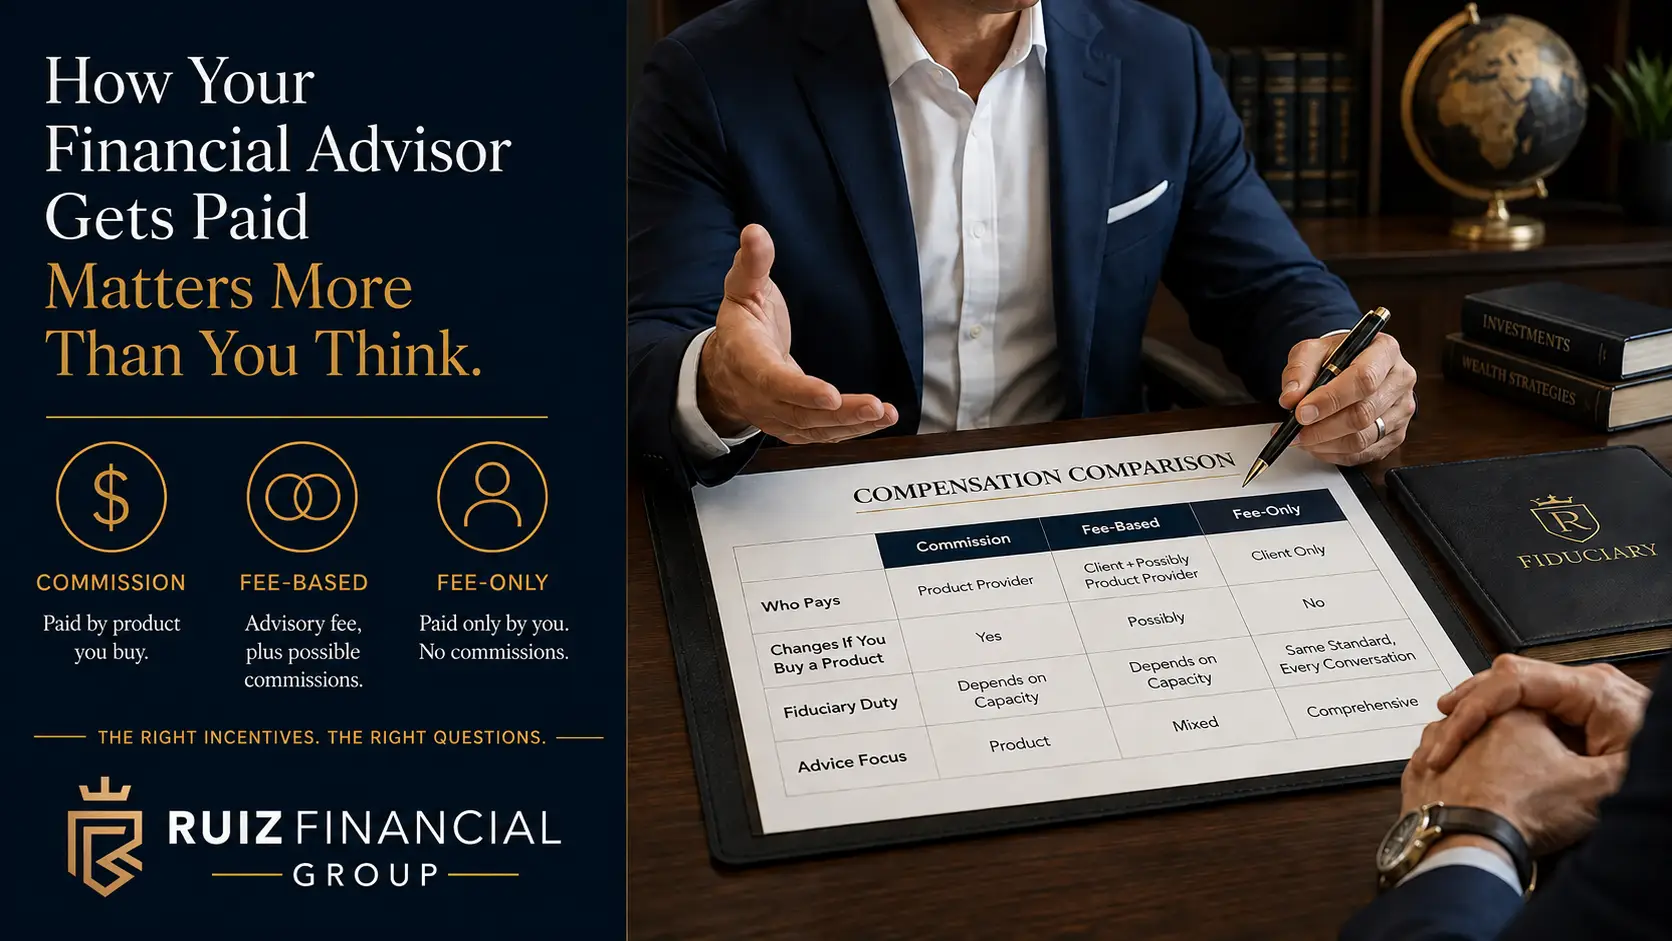
“Fee-Only” and “Fee-Based” Are Not the Same Thing
This is where the terminology gets genuinely confusing. “Fee-Only” and “fee-based” sound almost interchangeable. They’re not.
Under the Fee-Only model used by members of the National Association of Personal Financial Advisors (NAPFA), compensation comes only from clients. NAPFA’s standards prohibit members from taking commissions or other compensation tied to a client buying or selling a financial product. Fee-Only advisors can still charge in different ways, including an asset-management fee, a flat planning fee, or an hourly fee, but their compensation comes from their clients rather than from companies paying them to sell financial products.
A fee-based advisor may charge advisory fees and still be able to earn commissions or other compensation in a separate capacity. That doesn’t mean the advice is bad. It means you need to know which hat the person is wearing at any given moment, because the financial relationship can shift mid-conversation without the person across the table changing at all.
Ask When Your Advisor Is Acting as a Fiduciary
The word fiduciary gets used constantly in this industry, but most consumers never learn what it actually means beyond “good word to see on a website.” A fiduciary is generally expected to put your interests ahead of their own when giving you fiduciary advice.
The right question isn’t “Are you a fiduciary?” It’s: “When you give me advice, are you acting as a fiduciary, and are there times when you’re not?”
That second question matters a lot for professionals who wear more than one hat. Someone who is both an investment adviser representative and affiliated with a broker-dealer can have advisory relationships and brokerage relationships at the same time. The SEC has said directly that which standard applies can depend on the account, the services, the compensation, and the capacity the person is acting in at that moment. NAPFA takes a more specific stance for its own members: NAPFA-Registered Financial Advisors must work in a Fee-Only capacity, put client interests first, and either eliminate conflicts or disclose them fully.
The label alone isn’t enough. You should know which standard applies when that person is giving you advice.
Some Compensation Is Easier to See Than Others
Some forms of financial-product compensation are fairly easy to understand. Most people know an insurance professional earns a commission when a policy sells. Many know an annuity can carry compensation for whoever sold it.
Mutual funds are trickier. Some carry sales charges. Some carry ongoing 12b-1 fees paid out of the fund’s own assets, which can fund distribution, marketing, or shareholder-service expenses, and can be part of what the selling firm earns. FINRA specifically calls out 12b-1 fees as a cost investors should understand before buying a fund.
Nobody hands you a bill that reads:
Advisor compensation: $___
The cost is often baked into the investment itself. That’s why “How much do I pay you?” isn’t actually the whole question. A better one is: “Are you or your firm receiving any other compensation because of the investments, insurance, or other decisions I make?” How the money moves matters, even when you never see a check leave your account.
Fee-Only Does Not Mean Conflict-Free
And Fee-Only doesn’t mean conflict-free. No compensation model eliminates every potential conflict. An advisor paid on assets under management has an obvious interest in continuing to manage those assets. An advisor charging a planning fee has an interest in keeping the planning relationship going. Those conflicts should be recognized and disclosed just like any other.
What the Fee-Only structure removes is one specific category: compensation tied to selling a product or implementing a particular recommendation. That’s the part I care about, because financial planning goes well past investments. I’ve seen this with physicians and dentists who bought whole life insurance during residency after it was presented as part of a retirement strategy. In some cases, they understood the policy far better than they understood how the person recommending it was compensated. If I’m reviewing someone’s retirement, taxes, insurance, estate plan, and investments together, I want the recommendation to start with what their life actually calls for, not with what product happens to be sitting on the shelf.
I’m not going to pretend Fee-Only is some perfect system, because it isn’t. What it does is make the relationship a lot easier to see clearly, which is worth something on its own.
You Shouldn’t Have to Wonder Why the Recommendation Was Made
Really, this comes down to trust. If you’re paying someone directly for advice, it shouldn’t feel strange to also wonder whether a specific recommendation happens to increase that person’s paycheck. Compensation is only one piece of the picture, but it’s a piece worth having in front of you before you decide anything.
If your advisor is doing real comprehensive planning, you should be able to talk about investments, insurance, taxes, retirement, and estate issues in the same conversation without wondering whether their role, or their incentive, quietly changed halfway through.
Before Choosing an Advisor, Ask Better Questions
You don’t need to understand every regulation in financial services. You don’t need to memorize the jargon. And no single answer tells you whether an advisor is right for you. But clear answers to a handful of questions will tell you a lot:
How are you compensated, and what will I actually pay for your services?
Are there other costs I might pay beyond your advisory fee?
Do you receive commissions, referral fees, revenue sharing, or other third-party compensation?
When you’re advising me, are you acting as a fiduciary? Are there times you’re not?
What conflicts of interest should I know about, and how do you disclose or manage them?
An advisor should be able to answer each of these clearly. The answers should be plain enough to understand without decoding industry language.
These aren’t just questions for someone shopping for a new advisor, either. If you already work with someone and can’t confidently answer them yourself, ask. You might find out you already have exactly the relationship you thought you had. Or you might find out there’s a piece of it you never fully understood. Either way, you’re better off knowing.
That’s really the question underneath all of this, and it’s one I ask myself when I’m giving advice: Would my recommendation be any different if I didn’t make any more or less money based on what the client decided to do?
Questions to Ask a Financial Advisor
For a broader version of this conversation, Ruiz Financial Group’s “Questions to Ask a Financial Advisor” is built to help you evaluate an advisor’s compensation, fiduciary obligations, conflicts, planning process, investment approach, and ongoing relationship. Use it with any advisor you’re considering, including us.